
BELMONT, CA — September 2, 2026 — Exact Ventures recently published its Session Border Controller, IP Multimedia Subsystem (IMS), and Next Generation Network (NGN) Voice Vendor Market Share, Total Market, and 5-Year Forecast Analysis for 2Q 2026.
Voice infrastructure markets showed mixed results in 2Q26. The Session Border Controller (SBC) market rebounded sequentially, with growth in both the enterprise and service provider segments, and was roughly flat compared with a year ago. The IMS market held steady from the prior quarter but remained well below year-ago levels, and we have lowered our 2026 outlook. Both markets are dealing with the same problem. Operators are moving budget toward AI infrastructure. At the same time, AI-driven demand for memory and servers has raised the cost of cloud-native deployments, which makes the return on investment harder to justify. As a result, some operators are choosing to extend the life of their existing physical and virtual systems rather than move to cloud-native platforms now.
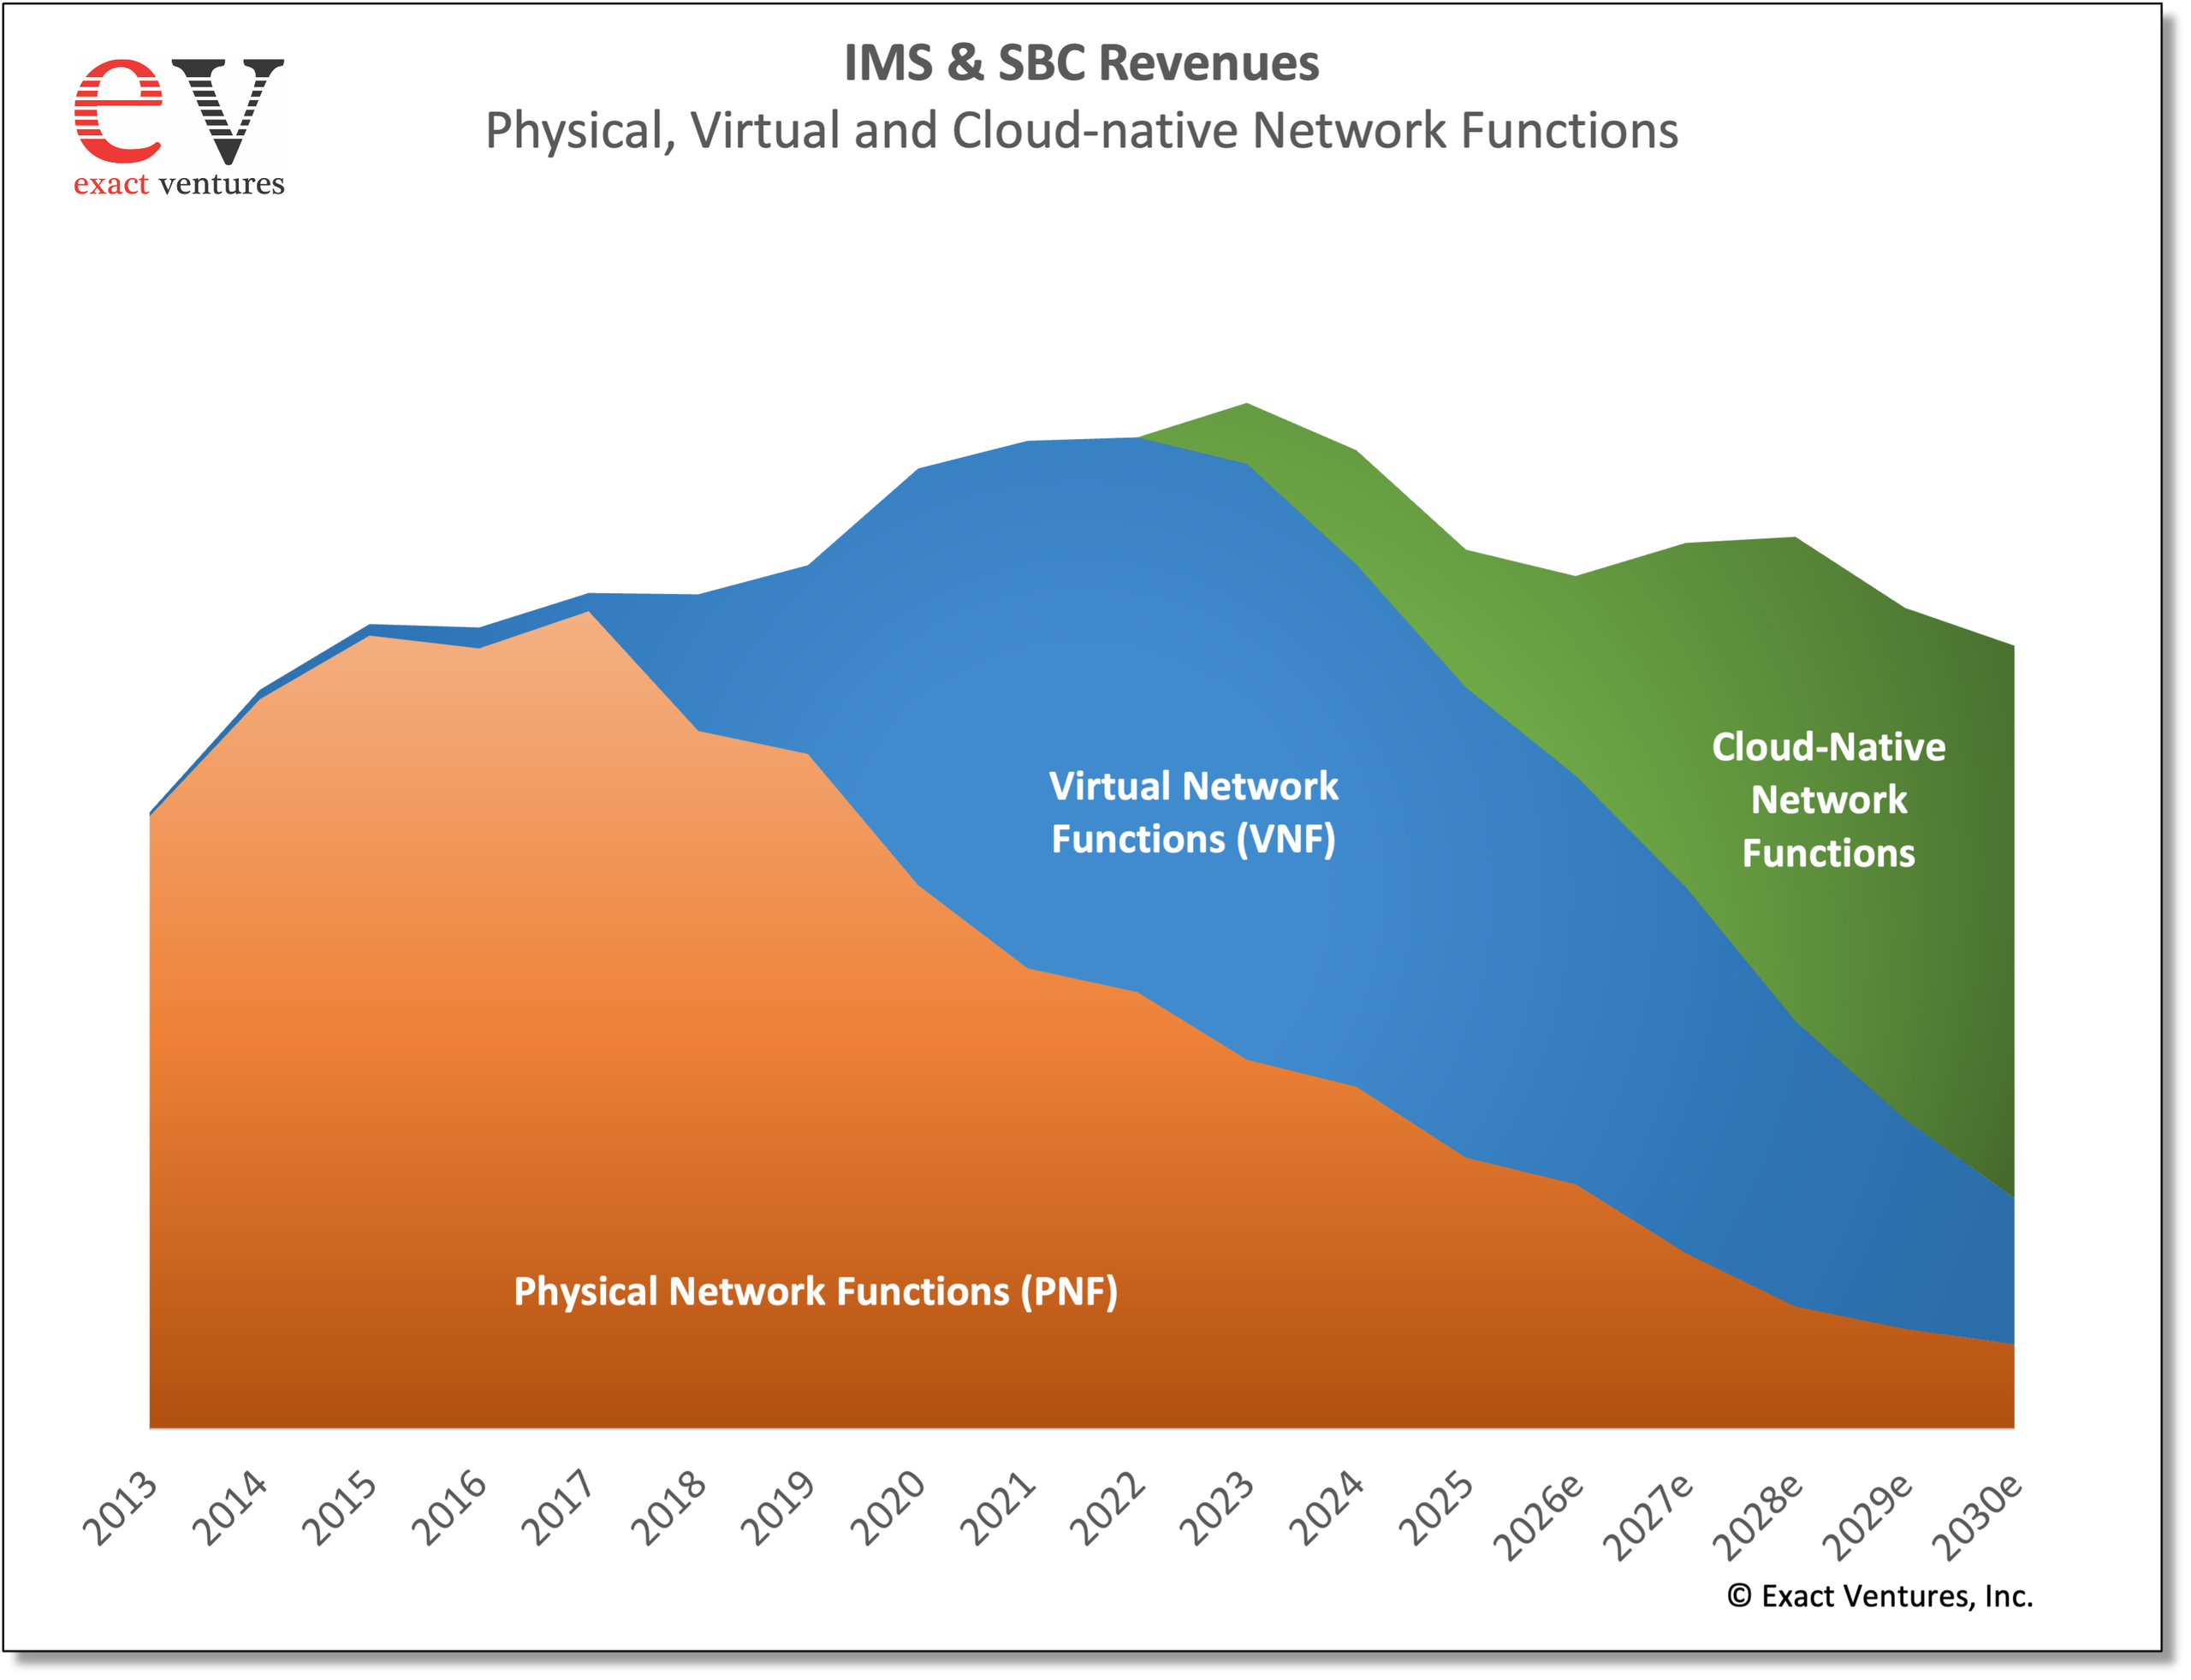
The longer-term drivers remain in place. Outside North America, operators are still migrating from 2G/3G to IMS and VoLTE, both to prepare for 5G standalone services and to free spectrum for 4G and 5G. A large installed base of older IMS equipment is being modernized to virtual and cloud-native systems. Operators are also investing in security and fraud prevention, and in network APIs that open voice capabilities to third-party developers. New services are emerging on top of IMS, including 5G New Calling over the IMS data channel and AI-enabled features such as real-time translation and in-call assistants. Cloud-native adoption is still moving forward, though higher hardware costs are slowing its pace, and IMS is expected to remain the foundation for voice as the industry moves toward 6G.
That migration continues to shrink the legacy NGN voice market, which includes softswitches, media gateways and NGN voice application servers. NGN sales declined again in 2Q26 and were down sharply from a year ago, with both wireline and wireless (2G/3G) voice falling. As operators move to all-IP and cloud-native architectures, spending is moving to IMS and to SBCs, which also bridge TDM and IP networks. We expect both NGN segments to decline further in 2026. Replacement demand will slow the decline but not reverse it.
In the enterprise, SBC demand reflects both new opportunities and real headwinds. Trade policy and geopolitical uncertainty are weighing on spending. AI is also moving enterprise budgets away from headcount and toward compute, which reduces the need for voice lines. At the same time, enterprises are investing in voice orchestration that routes calls across PBX, UCaaS, Microsoft Teams and Zoom, often with conversational AI handling intent recognition and routing. The SBC is central to that architecture because it maintains call quality, security and SIP interworking across these platforms. Growth in cloud-based UC and contact center services, along with a gradual shift to SBC-as-a-service, continues to support the market. Service provider wireline voice is expected to keep declining as voice subscriptions fall.
For more information or to request the full report, contact:
Greg Collins
Exact Ventures
greg@exactventures.com
Get in touch